

CRM for Mortgage Brokers: HighLevel for Loan Officers
A CRM for mortgage brokers keeps pre-approved buyers warm through a long house hunt and updates realtor partners at each milestone. It also chases missing documents and turns past clients into reviews, referrals and refinances. HighLevel does this with pipelines, workflows and texting, plus a power dialer and Voice AI. However, it is not a loan origination system, so applications, pricing and disclosures stay in Encompass, Arive or your LOS.
In March, Kevin and Ana Ortiz get pre-approved with your brokerage. Then they spend four months touring homes, and nobody from your office checks in. In July they finally find the house, and their realtor sends them to a lender who kept her posted on every file. Your pre-approval simply expired in silence. A CRM for mortgage brokers exists to stop exactly that: long cycles, quiet months and partners who never hear back.
This guide is for mortgage brokers, loan officers and small teams, plus the agencies that build their systems. First, you will see a loan pipeline, a realtor partner board and three automations with real triggers. Then come the official HighLevel snapshot, the setup order, real costs and the compliance basics: RESPA, TCPA and NMLS.
One boundary matters from the start. HighLevel is the relationship and marketing layer, not a loan origination system. In fact, it does not take the application, price loans, pull credit or produce disclosures. So keep Encompass, Arive or your current LOS for the loan file, and use HighLevel for everything around it.
Leer en español: CRM para brokers hipotecarios · Ler em português: CRM para correspondente bancário · Part of GoHighLevel by industry
What a mortgage broker needs from a CRM
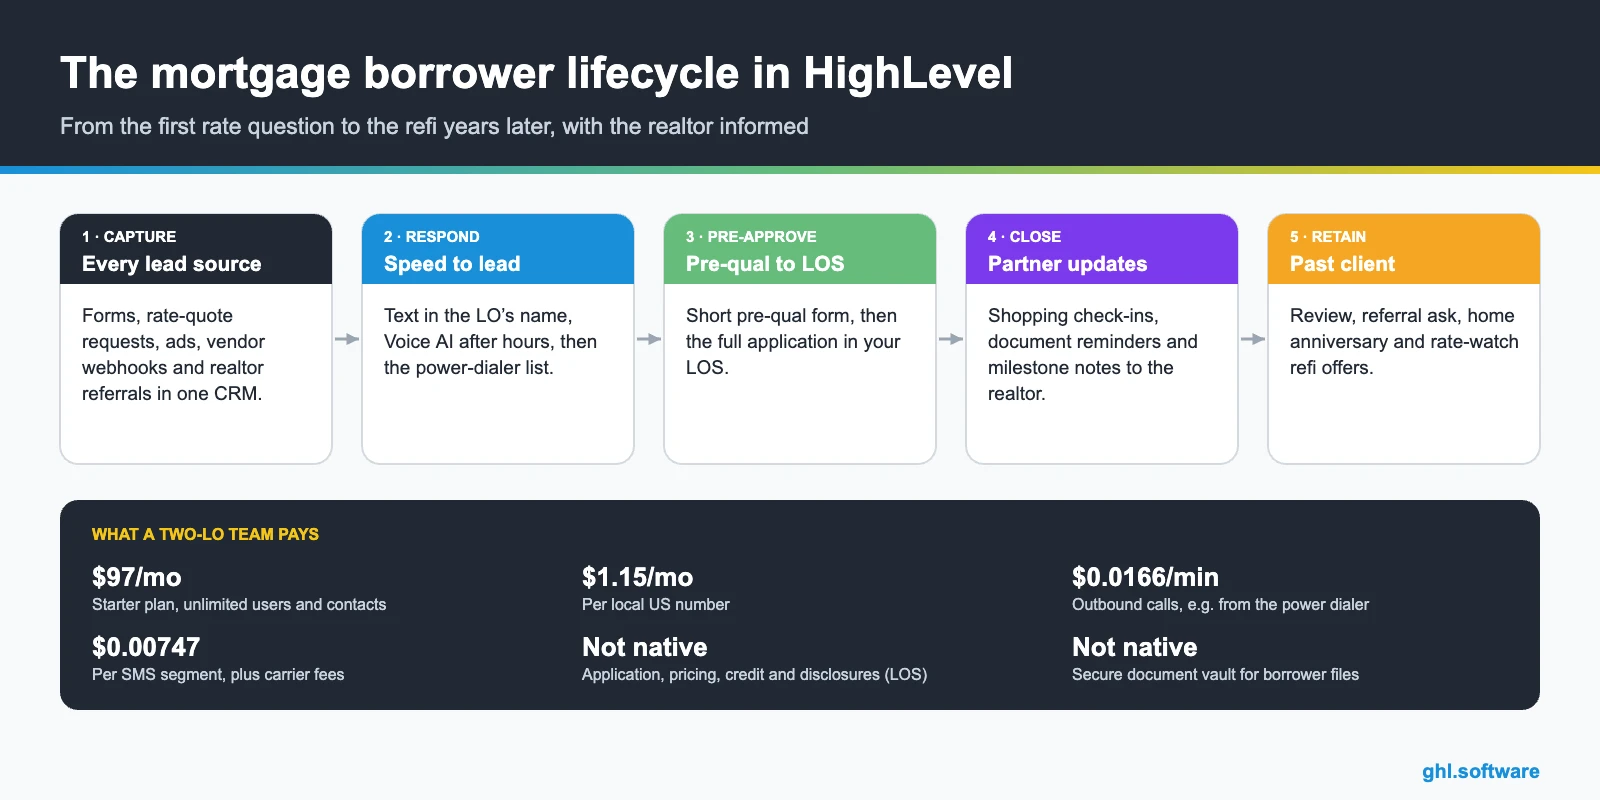
The LOS manages the loan. The CRM, instead, manages the borrower and the partner before, during and long after that loan. So a CRM for mortgage brokers has to respond fast, stay in touch for months and remember dates for years. Here is how HighLevel covers each job.
Common loan-office problems and how HighLevel solves them
Few loans are lost on the rate sheet. Instead, they slip away in the gaps: the lead nobody called, the buyer who went quiet and the realtor who never got an update. So the table maps each gap to the feature that closes it in a CRM for mortgage brokers.
| Problem | What HighLevel does | Feature |
|---|---|---|
| Internet leads call five lenders | Texts within a minute, then adds the lead to a dialer list | Workflows + power dialer |
| Pre-approved buyers go quiet | Checks in every 14 days until they are under contract | Pipeline stage trigger + waits |
| Realtors keep asking for updates | Emails the linked partner at each milestone | Custom fields + workflows |
| Borrowers forget documents | Texts the missing-items list until everything is in | Tasks + SMS |
| Past clients forget you | Sends anniversary notes and rate-watch updates | Custom date reminder + email |
| Few reviews after closing | Asks for a Google review a week after funding | Reputation management |
| No view of lead sources | Shows pre-approvals and funded loans by source and partner | Reporting |
The loan pipeline in a CRM for mortgage brokers
A mortgage passes through many hands, but the borrower only sees silence or progress. So the loan board in a CRM for mortgage brokers should mirror the milestones that borrowers and realtors care about. It does not need every LOS status. The loan amount is the opportunity value, while the source and the partner sit in custom fields.

| Stage | What moves the card here |
|---|---|
| New lead | A form, rate-quote request, webhook, call or partner referral creates the opportunity |
| Contacted | The loan officer reaches the borrower, which stops the speed-to-lead cadence |
| Pre-qual | A short pre-qual form or discovery call captures goals, price range and timeline |
| Application in LOS | The borrower completes the application in your LOS; the CRM only logs the date |
| Pre-approved / shopping | The LO issues the pre-approval, which starts the shopping nurture and partner updates |
| Under contract | The borrower or realtor reports an accepted offer |
| Processing & underwriting | The file moves through processing, conditions and appraisal |
| Clear to close | Final approval arrives and the closing date is set |
| Funded | The loan funds; review, referral and past-client workflows start |
Run two more boards next to it. A Realtor partners pipeline tracks agents from the first coffee to active partner. Meanwhile, a Refi pipeline catches past clients who answer rate-watch messages, so purchase numbers stay clean.
For a look at the opportunities view and workflow maps inside HighLevel, this breakdown from HighLevel for Mortgage Pros covers both, as its title says.
Video: GHL Weekly Breakdown: HighLevel for Loan Officers - Workflow Mini Map, Opportunities, and More! · HighLevel for Mortgage Pros
Three automations every loan officer should run
These workflows cover the moments where brokers lose the most business: the first minute, the long months after pre-approval and the years after closing. Build them once in your CRM for mortgage brokers, then reuse them for every LO on the team.
Speed to lead with a power-dialer fallback
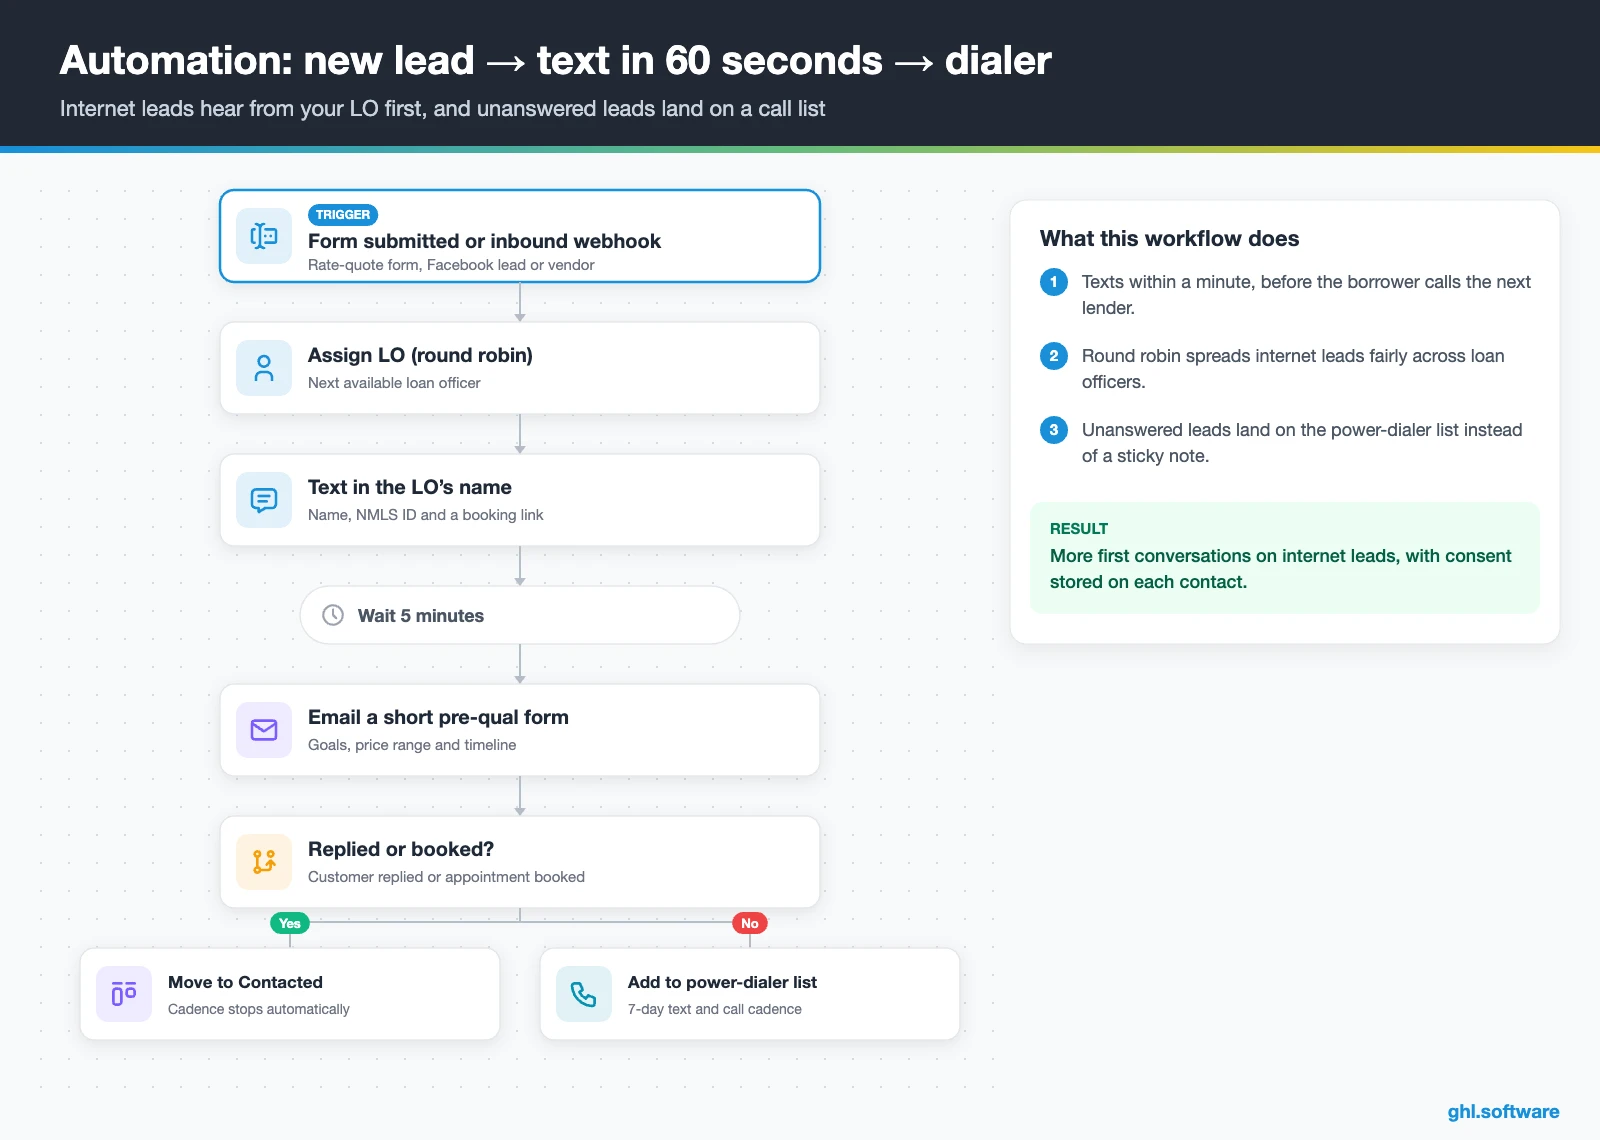
Usually, the trigger is a new lead from a form, a Facebook lead form or a lead vendor’s inbound webhook. The workflow creates the opportunity in “New lead”, assigns a loan officer by round robin and texts the borrower in that LO’s name. Each text also carries the LO’s name, NMLS ID and a booking link.
If the borrower does not reply within five minutes, an email follows with a short pre-qual form. After that, the contact joins the LO’s power-dialer list, and a seven-day cadence of texts and calls continues. As soon as the borrower replies or books, the cadence stops. As a result, your office talks to the borrower before the next lender does.
Pre-approval follow-up and the realtor loop
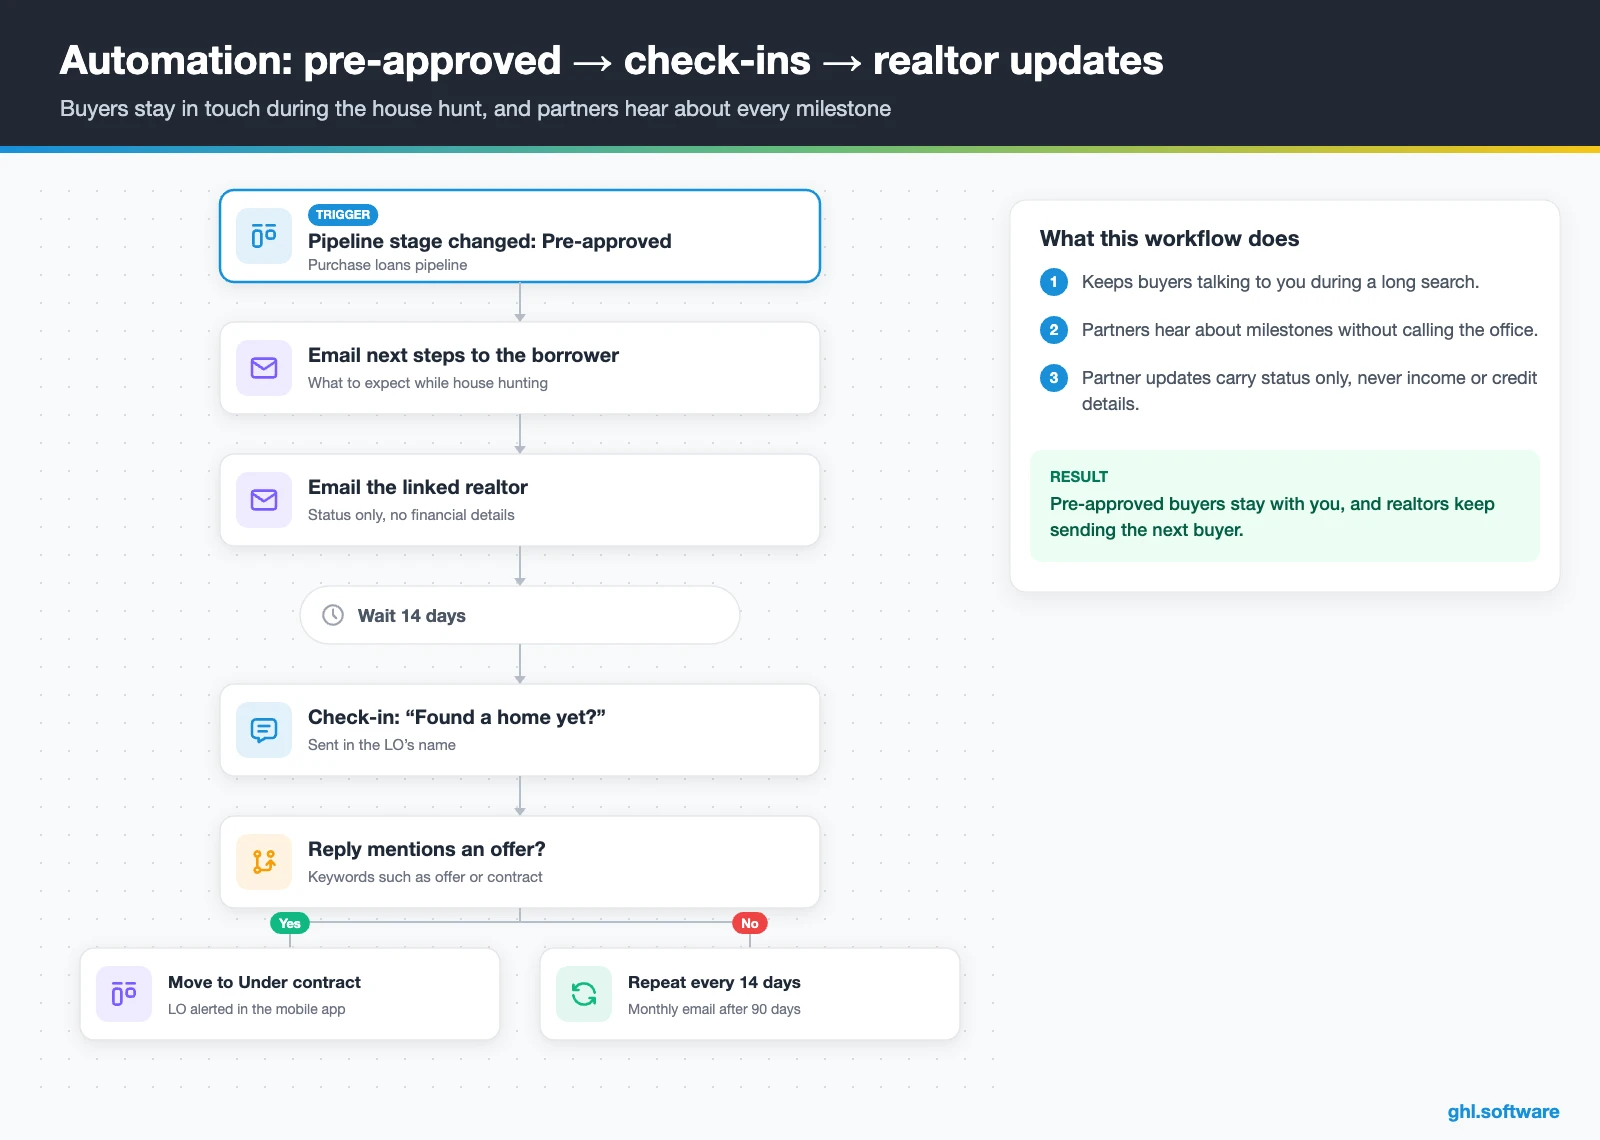
This workflow starts when an opportunity moves to “Pre-approved / shopping”. First, it emails the borrower the next steps and then sends the linked realtor a status update, never income or credit details. Then, every 14 days, a short text asks how the search is going.
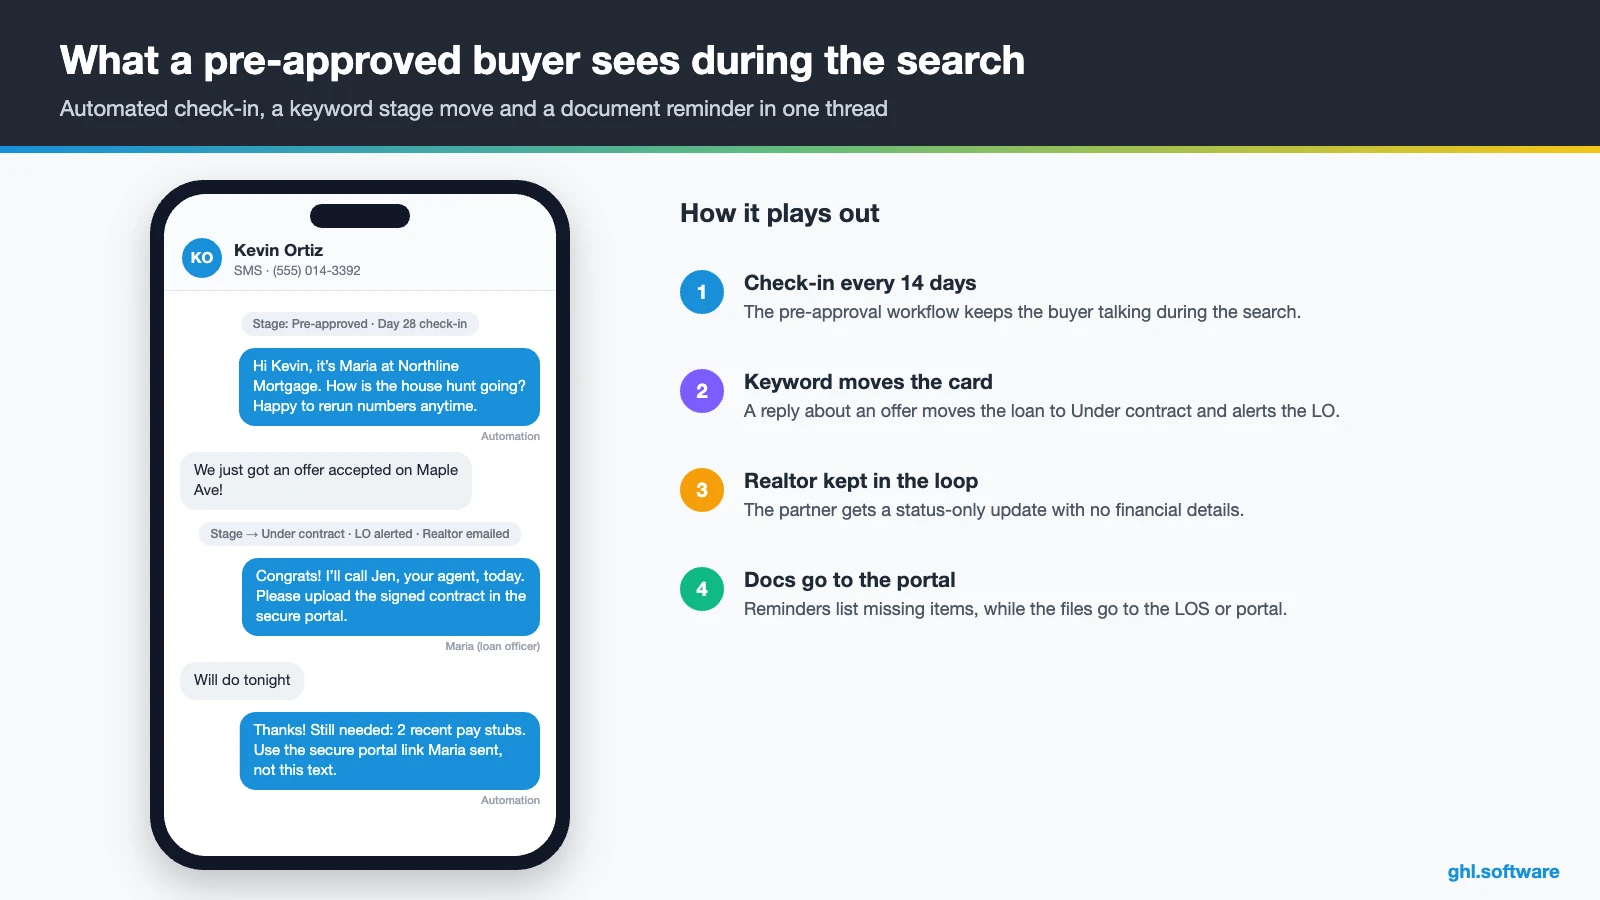
If the reply mentions an offer or a contract, the workflow moves the card to “Under contract” and alerts the LO. Later milestones, such as clear to close, send the realtor another short update. If nothing moves for 90 days, the borrower joins a monthly market email. That way pre-approved buyers stay with you through a long house hunt.
Funded loan → review, referral and rate watch
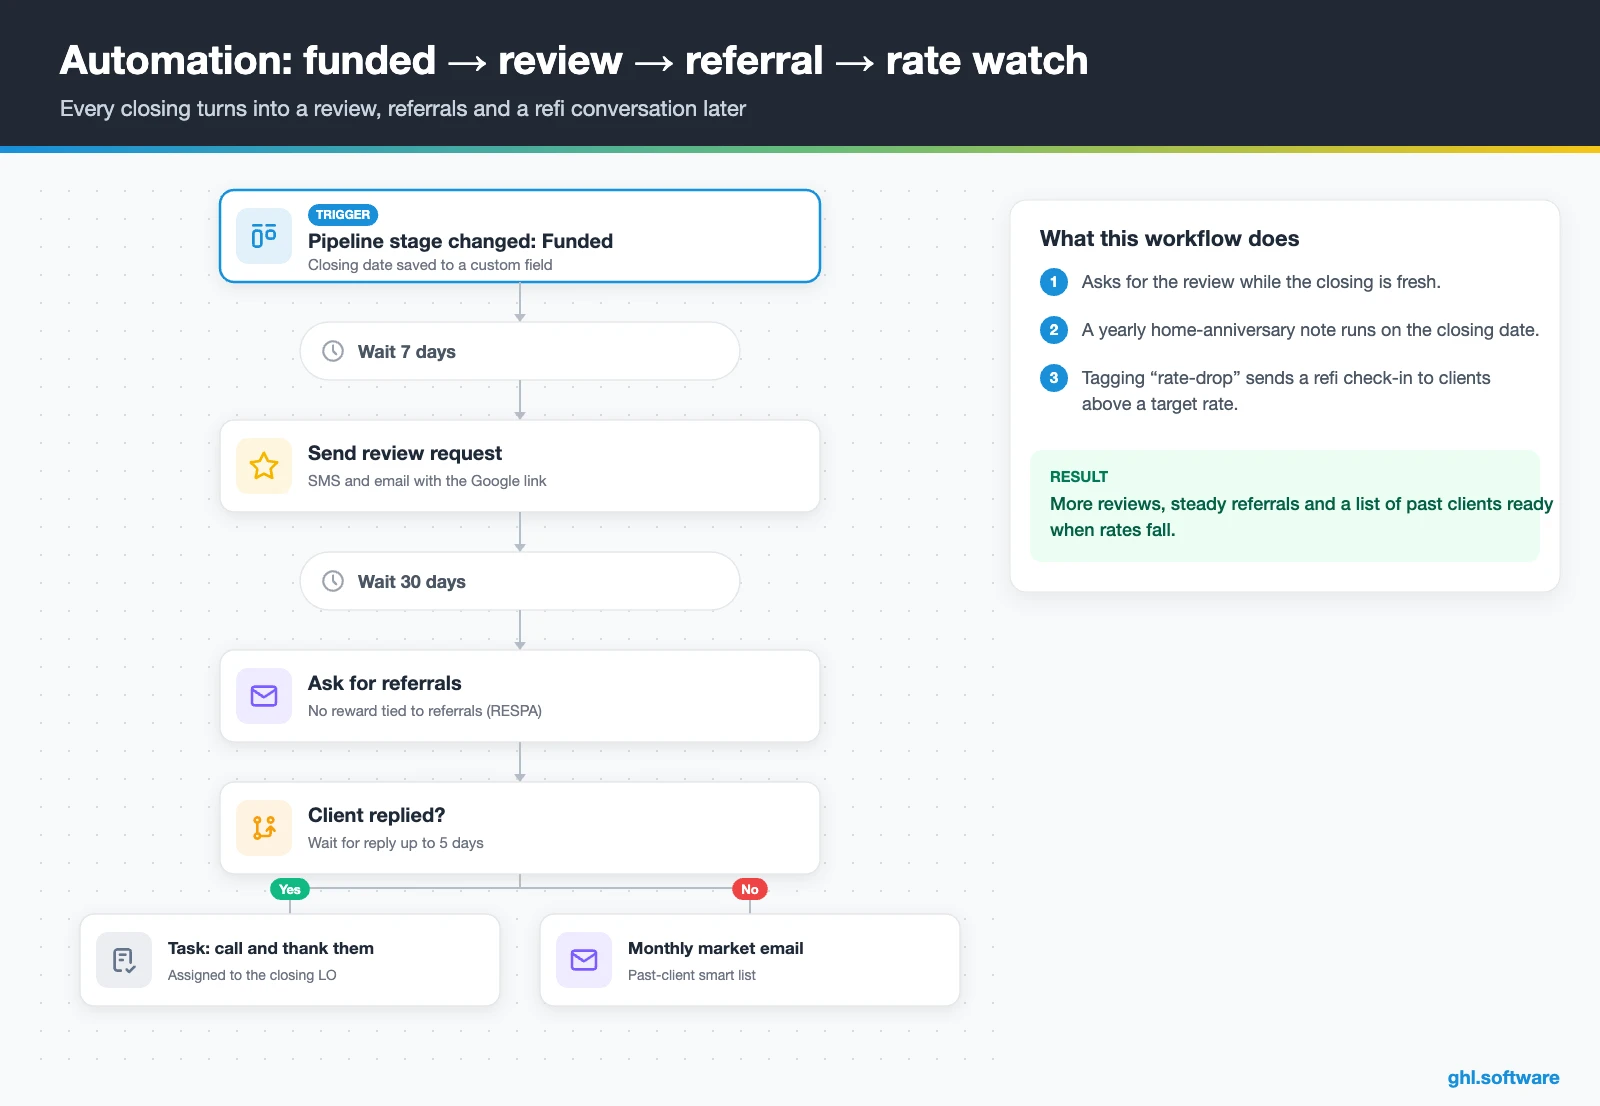
When the card moves to “Funded”, the workflow saves the closing date and waits seven days. Then it sends every client a review request by SMS and email, and any unhappy reply goes to the branch manager. Thirty days later it asks for referrals, with no reward tied to the referral. From then on, the client gets a monthly market email and a home-anniversary note each year.
Rate watch is the part that pays later. A “Note rate” field lets you build a smart list of past clients above a target rate. When rates fall, you tag that list, and a broadcast invites them to review refinance options. After that, replies create an opportunity in the Refi pipeline, and the LO takes it from there.
Document-collection reminders without storing documents
Chasing paperwork eats hours every week, so let your CRM for mortgage brokers send the reminders. In HighLevel, a “Docs needed” field lists the missing items, such as pay stubs or bank statements. A workflow texts the borrower that list every two days and creates a processor task when they reply. However, the files themselves belong in your LOS or a secure portal. HighLevel is not a secure document vault, so don’t collect tax returns or IDs through form uploads.
Start with the snapshot and the pipeline from this guide, then add the automations one by one. The extended trial comes with our bootcamp link.
Start the 30-day trialAffiliate link. I may earn a commission at no extra cost to you.
Texting, calling and AI for loan officers
Borrowers rarely wait for a callback. They text, call another lender or fill out a second form. HighLevel keeps SMS, email, WhatsApp, Facebook and Instagram DMs and web chat in one inbox per borrower. In a shared CRM for mortgage brokers, an assistant can answer a status question, and the LO sees the whole thread before calling. For Spanish-speaking borrowers, however, WhatsApp costs $10 a month per sub-account plus Meta fees.
AI handles the after-hours load. Conversation AI answers common questions and books a call, while Voice AI picks up the phone. Still, keep rates, terms and approvals with licensed people, and never let a bot quote a rate. AI is billed per use or as a monthly plan, as our AI Employee pricing guide explains.
To see the calling side, this video from HighLevel for Mortgage Pros breaks down HighLevel’s power dialer for loan officers, according to its title.
Video: Mortgage Lead Dialer - Breaking Down HighLevel's Power Dialer Functionality for Loan Officers · HighLevel for Mortgage Pros
What HighLevel’s official Mortgage Lender snapshot includes
HighLevel publishes a free Mortgage Lender playbook with a matching snapshot. However, it uses the same generic template as other industries, with the names swapped. So treat it as a starter kit, not a finished CRM for mortgage brokers. Out of the box you get:
- A “Mortgage Lender” website with Home and Link in Bio pages, plus a chat widget.
- A “Mortgage Lender Offer” funnel: an opt-in step, then an appointment booking page.
- The “Marketing Form – Claim Offer” form and a “Marketing Pipeline”.
- The “New Lead Nurture (Fast 5) – Claim Offer” workflow (email, SMS and a voicemail drop) and “Long Term Nurture”.
- Service calendars tagged “Mortgage Lender Services”, a general calendar and an event calendar.
- Voice AI prompts for call handling, appointment setting and FAQs.
What it lacks is the mortgage logic. Moreover, the guide lists no pipeline stages and names only two of its six workflows. It also has no pre-approval, application, partner or rate-alert workflows. So you still build the loan, partner and refi pipelines, the custom fields and the automations above. Third-party mortgage snapshots exist as well, but review them closely, because they are not HighLevel’s own. Finally, once your build works, save it as your own snapshot for each new LO.
How to set up HighLevel for a mortgage brokerage
Follow this order when you set up your CRM for mortgage brokers, so routing, consent and partner updates work from day one.
- Create the sub-account. Load the Mortgage Lender snapshot or start blank. Add the company profile, time zone and a branded sending domain.
- Add loan officers and staff. Create one user per LO, processor and assistant. Put each LO’s NMLS ID in their signature and email templates.
- Connect phones and A2P. Buy local numbers, register A2P 10DLC, then set up the power dialer, call recording notices and missed call text back.
- Create custom fields. Loan type, purpose, price range, loan amount, note rate, closing date, realtor partner, docs needed and consent date.
- Import past clients and partners. Upload CSVs with closing dates, rates and partner tags, and keep do-not-contact flags intact.
- Build three pipelines. Loan, Realtor partners and Refi, with the stages above and clear lost reasons.
- Publish forms and funnels. Build a short pre-qual form (not a full application), a rate-watch signup and a partner page with funnels.
- Turn on workflows and reporting. Activate the three automations and document reminders, then track leads, pre-approvals and funded loans by source.

What a CRM for mortgage brokers costs on HighLevel
HighLevel charges a flat plan price, not a fee per loan officer, and every plan includes unlimited users and contacts. So a team of five LOs pays the same base price as one. Usage then comes on top: numbers, texts, calls, email, WhatsApp and AI.
For example, take a two-LO team on Starter ($97) with two local numbers ($2.30) and 5,000 SMS segments (about $37 plus carrier fees). Then add 3,000 outbound dialer minutes (about $50) and 15,000 emails (about $10). As a result, that team lands near $197 a month, plus A2P fees. With the $97 AI plan, it reaches about $294. Most small broker shops spend between $180 and $400 a month, and our pricing guide has the full breakdown.
GoHighLevel plans compared
| Starter | Unlimited | Agency Pro | |
|---|---|---|---|
| Price | $97/month | $297/month | $497/month |
| Annual | $970/year | $2,970/year | $4,970/year |
| Sub-accounts | 3 | Unlimited | Unlimited |
| Contacts and users | Unlimited | Unlimited | Unlimited |
| All core features | Yes | Yes | Yes |
| White label web app | Yes | Yes | Yes |
| API access | Basic | Basic | Advanced, agency-level keys |
| Rebill phone and email | No | At cost | With markup |
| Rebill AI usage | No | No | Yes |
| SaaS Mode and automated sub-accounts | No | No | Yes |
| User and agent reporting | No | No | Yes |
| Support | 24/7 | 24/7 | 24/7 |
Usage costs on top of the plan
| Item | Official price | When you pay it |
|---|---|---|
| Local phone number (US/Canada) | $1.15/month | Each number for SMS and calls |
| SMS (US/Canada) | $0.00747 per segment + carrier fees | Every text sent or received |
| Calls (US) | $0.0166/min outbound, $0.01165/min inbound | Calls through LC Phone |
| A2P 10DLC registration | $22.50 one-time (low volume) + monthly campaign fee | Before texting US numbers |
| Email (LC Email) | $0.675 per 1,000 emails | Campaigns and workflow emails |
| $10/month per sub-account + Meta fees | If you use WhatsApp inside HighLevel | |
| AI | Pay-per-use, or $50 or $97/month per sub-account | Voice AI, Conversation AI and other AI tools |
| Premium workflow steps | $0.01 per run after 100 free | Webhooks, Google Sheets, Slack, app actions |
Honest limits: HighLevel is not a loan origination system
HighLevel is a strong relationship and marketing layer. Still, a CRM for mortgage brokers cannot do the LOS’s job, so check these gaps first.
- No application, pricing or credit. There is no 1003/URLA, pricing engine or credit pull. Those stay in Encompass, Arive or your LOS.
- No disclosures. Also, TRID disclosures and the loan file stay in the LOS.
- No native LOS connector that we could verify. Plan on webhooks, the API or an automation tool, and test every field.
- Not a secure document vault. Use your LOS or a secure portal for tax returns, IDs and bank statements.
- No ad-compliance archive. Instead, keep your own review and archive process for marketing materials.
So most brokers run both: the LOS for the loan and HighLevel for leads, partners and past clients. Here is how HighLevel compares with mortgage CRMs that loan officers often shortlist. Features change often, so confirm details with each vendor.
| HighLevel | Surefire | Jungo | Total Expert | |
|---|---|---|---|---|
| Main job | CRM, messaging, funnels and AI in one platform | Mortgage CRM and marketing | Mortgage CRM | Marketing and engagement for lenders |
| Built only for mortgage and lending | No | Yes | Yes | Yes |
| Unlimited users on every plan | Yes | Ask the vendor | Priced per user | Ask the vendor |
| Best fit | Brokers who want one flat-priced system for leads, partners and past clients | LOs who want mortgage-built marketing | LOs who want a mortgage-only CRM | Lenders that want enterprise marketing tools |
If your company already pays for Surefire or Total Expert, keep it. HighLevel can still add funnels, WhatsApp, Voice AI and review campaigns for a single LO or a small shop.
Compliance: RESPA, TCPA, A2P 10DLC and NMLS
The angle most guides miss: realtor co-marketing that stays RESPA-safe
Realtor partners send the best purchase loans, so brokers want to market with them. However, a referral relationship is exactly what RESPA Section 8 watches. Regulation X still allows “normal promotional and educational activities that are not conditioned on the referral of business”. Therefore, keep anything of value separate from who sends you loans.
In HighLevel, that means a few concrete habits. Track partners in their own pipeline, but never trigger a gift, credit or paid ad when a referral arrives. Build co-branded pages and market updates as education, and have compliance review any shared-cost deal first. Also, partner updates should carry status only, never borrower finances. Few guides about a CRM for mortgage brokers cover this, yet it is where partner marketing carries real risk. You can compare this setup with our other industry guides or browse the features hub.
Open a free account, load the pipeline and turn on the first automation today. The bootcamp walks you through the setup live.
Start the 30-day trialAffiliate link. I may earn a commission at no extra cost to you.
Frequently asked questions
What is the best CRM for mortgage brokers?
It depends on how you work. Mortgage-only CRMs such as Surefire, Jungo or Total Expert ship with lending content and workflows. HighLevel suits brokers and LOs who want leads, texting, a power dialer, Voice AI, funnels and past-client campaigns in one flat-priced platform. Whatever you choose, keep the loan file in your LOS and connect the two for key dates and stages.
Does HighLevel integrate with Encompass or Arive?
However, we found no native Encompass or Arive connector in HighLevel’s feature list. Most brokers connect them through webhooks, the HighLevel API or an automation tool, and sync a few fields such as stage, closing date and loan amount. Test each field before you rely on it. Many teams simply update the CRM stage by hand when the LOS status changes.
Can HighLevel replace my loan origination system?
No. HighLevel has no 1003/URLA application, pricing engine, credit pull or TRID disclosures, and it is not a secure document vault. It is the relationship and marketing layer around the loan: lead response, nurture, partner updates, reviews and past-client campaigns. So keep Encompass, Arive or your current LOS for the loan file itself.
Is co-marketing with realtors RESPA-compliant?
It can be, but it needs care. RESPA Section 8 bans giving or accepting anything of value for referrals of settlement business. Still, Regulation X allows normal promotional and educational activities that are not conditioned on referrals. So never tie gifts, paid ads or shared costs to who sends you loans, and ask your compliance team to review any co-marketing arrangement first.
Can I text mortgage leads legally?
Yes, with consent and registration. Under the TCPA, autodialed or prerecorded marketing texts and calls need prior express written consent, so store the consent proof on each contact. Texting from US local numbers also requires A2P 10DLC registration through HighLevel’s Trust Center. Honor STOP replies on every channel, and keep loan details out of text messages.
How do I nurture past clients for refinances and referrals?
First, save the closing date and note rate on each past client. A workflow then sends a review request a week after funding, a referral ask a month later and a home-anniversary note every year. When rates drop, tag the smart list of clients above your target rate and broadcast a refinance check-in. Replies open an opportunity in a Refi pipeline.
How much does a CRM for mortgage brokers cost on HighLevel?
The Starter plan costs $97 a month with unlimited users and contacts. Usage adds the rest: $1.15 per local number, SMS segments, dialer minutes, email and optional AI at $50 or $97 a month. As a result, a small team that texts and dials actively usually spends between $180 and $400 a month in total.
More industry guides
Sources: HighLevel Mortgage Lender playbook · CFPB: Regulation X § 1024.14 (RESPA Section 8) · eCFR: Regulation Z § 1026.36 (NMLSR ID on loan documents) · FCC: Telemarketing and robocalls · FTC: Gramm-Leach-Bliley Act · HighLevel help: A2P 10DLC registration · HighLevel help: WhatsApp pricing and billing · HighLevel help: Missed Call Text Back